Thinking About Waiting for Lower Mortgage Rates? Read This First.
If you've been thinking about buying a home in Bluffton, Hilton Head Island, or the surrounding South Carolina Lowcountry, but you're waiting for mortgage rates to drop before making your move, you're certainly not alone.
For many buyers, the thinking is simple: Why buy now if rates could be significantly lower next year?
The problem is that current forecasts don't necessarily support that strategy.
While mortgage rates will continue to fluctuate, experts aren't currently forecasting the dramatic decline many buyers have been hoping for. That doesn't mean everyone should rush out and buy a home today. It does mean that waiting solely for a much lower mortgage rate may be worth reconsidering.
Here's what today's data could mean for Lowcountry buyers.
1. Mortgage Rates Aren't Expected To Drop Dramatically
A lot of buyers are waiting for the return of mortgage rates in the 4% or 5% range.
According to data highlighted by Keeping Current Matters, a recent Clever-Best Interest survey found that 42% of people believe mortgage rates will fall below 5% this year.
Current expert forecasts tell a different story.
Forecasts from Fannie Mae, the Mortgage Bankers Association, and Wells Fargo show mortgage rates remaining relatively steady in the low-to-mid 6% range through at least mid-2027.
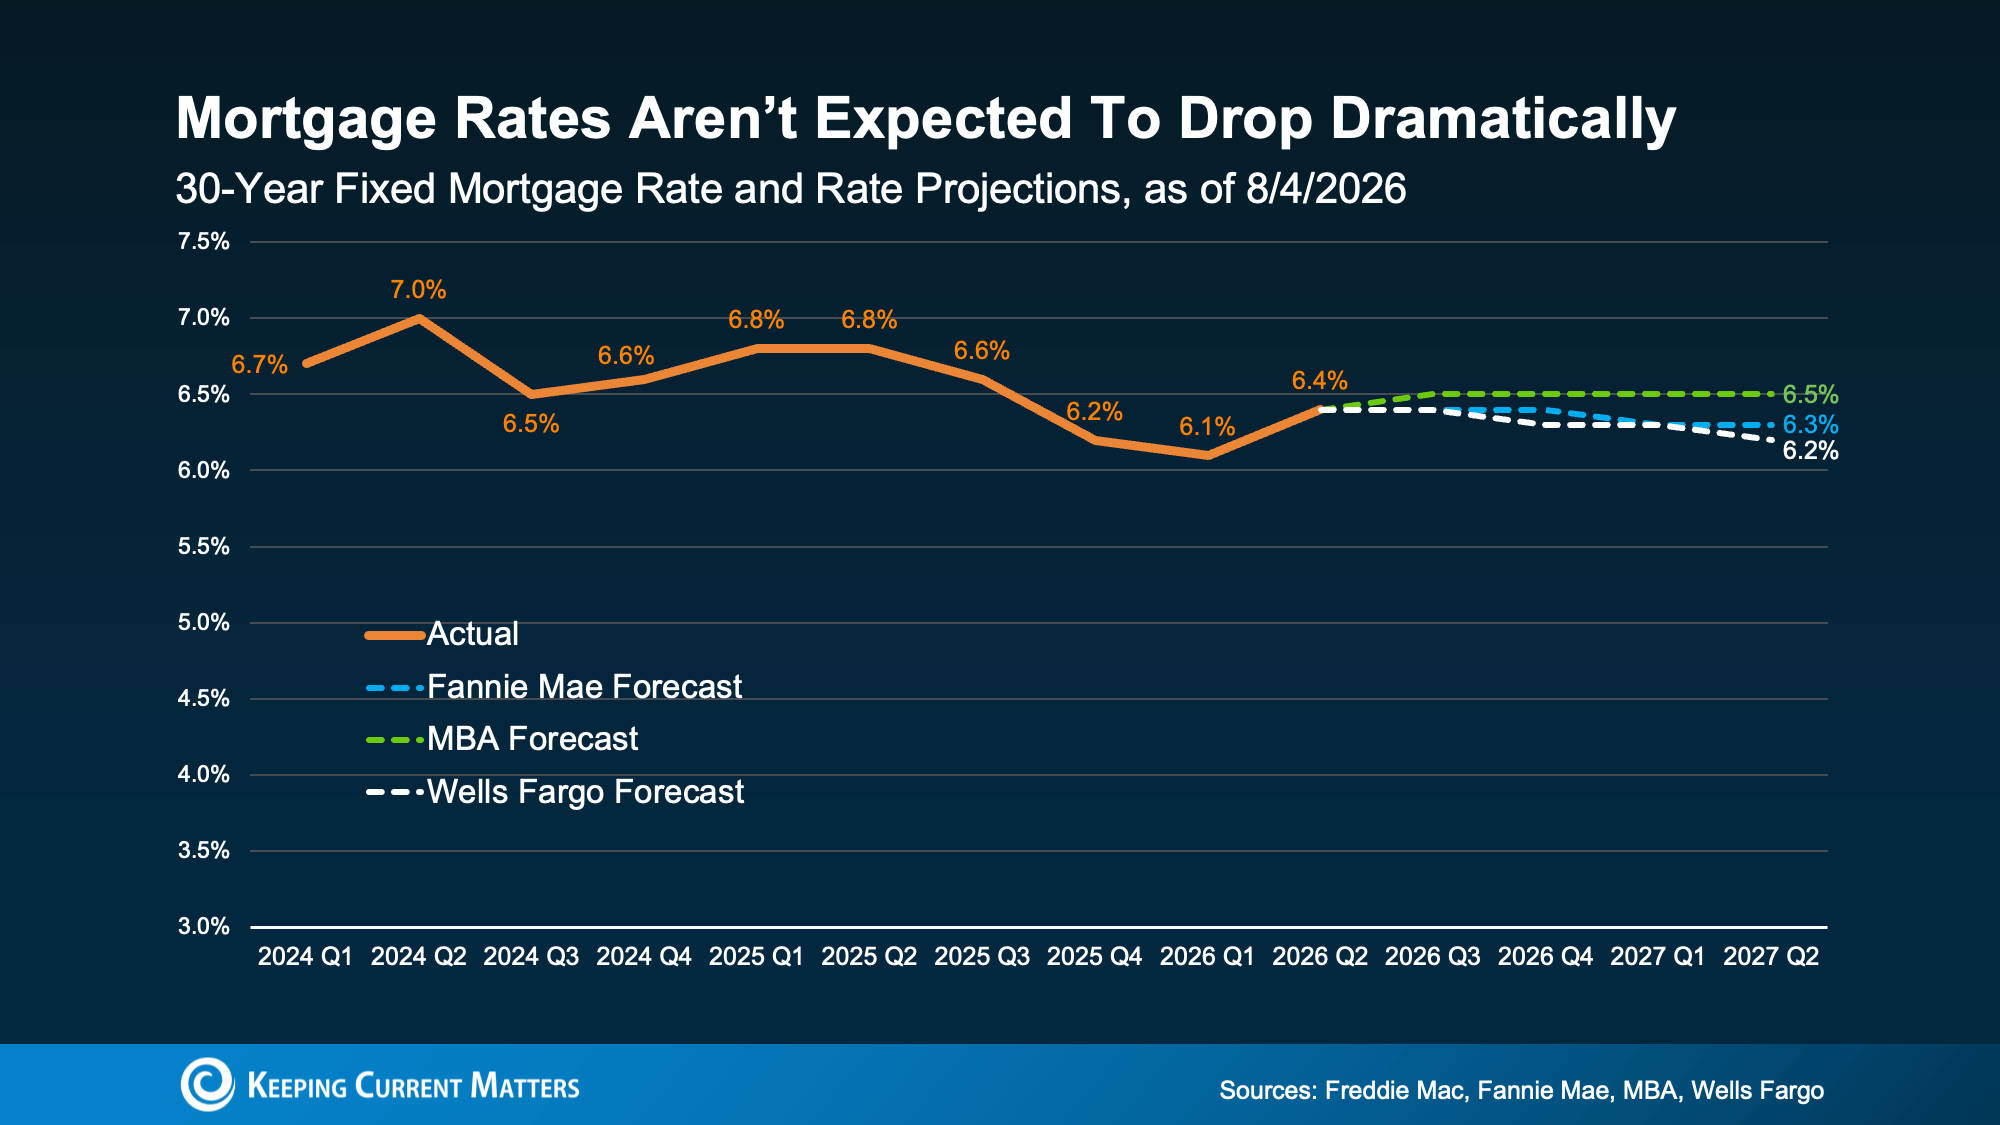
Source: Fannie Mae, Mortgage Bankers Association and Wells Fargo, via Keeping Current Matters
Could rates move lower? Absolutely.
Mortgage rates are influenced by inflation, Treasury yields, Federal Reserve policy, economic conditions, global events, and a long list of other factors. Predicting exactly where they'll be six months or a year from now is nearly impossible.
But there's an important difference between rates moving lower and rates dropping dramatically.
If you're waiting specifically for a return to the ultra-low mortgage rates we saw several years ago, today's forecasts suggest you could be waiting longer than expected.
2. Inflation Is Still Working Against Lower Mortgage Rates
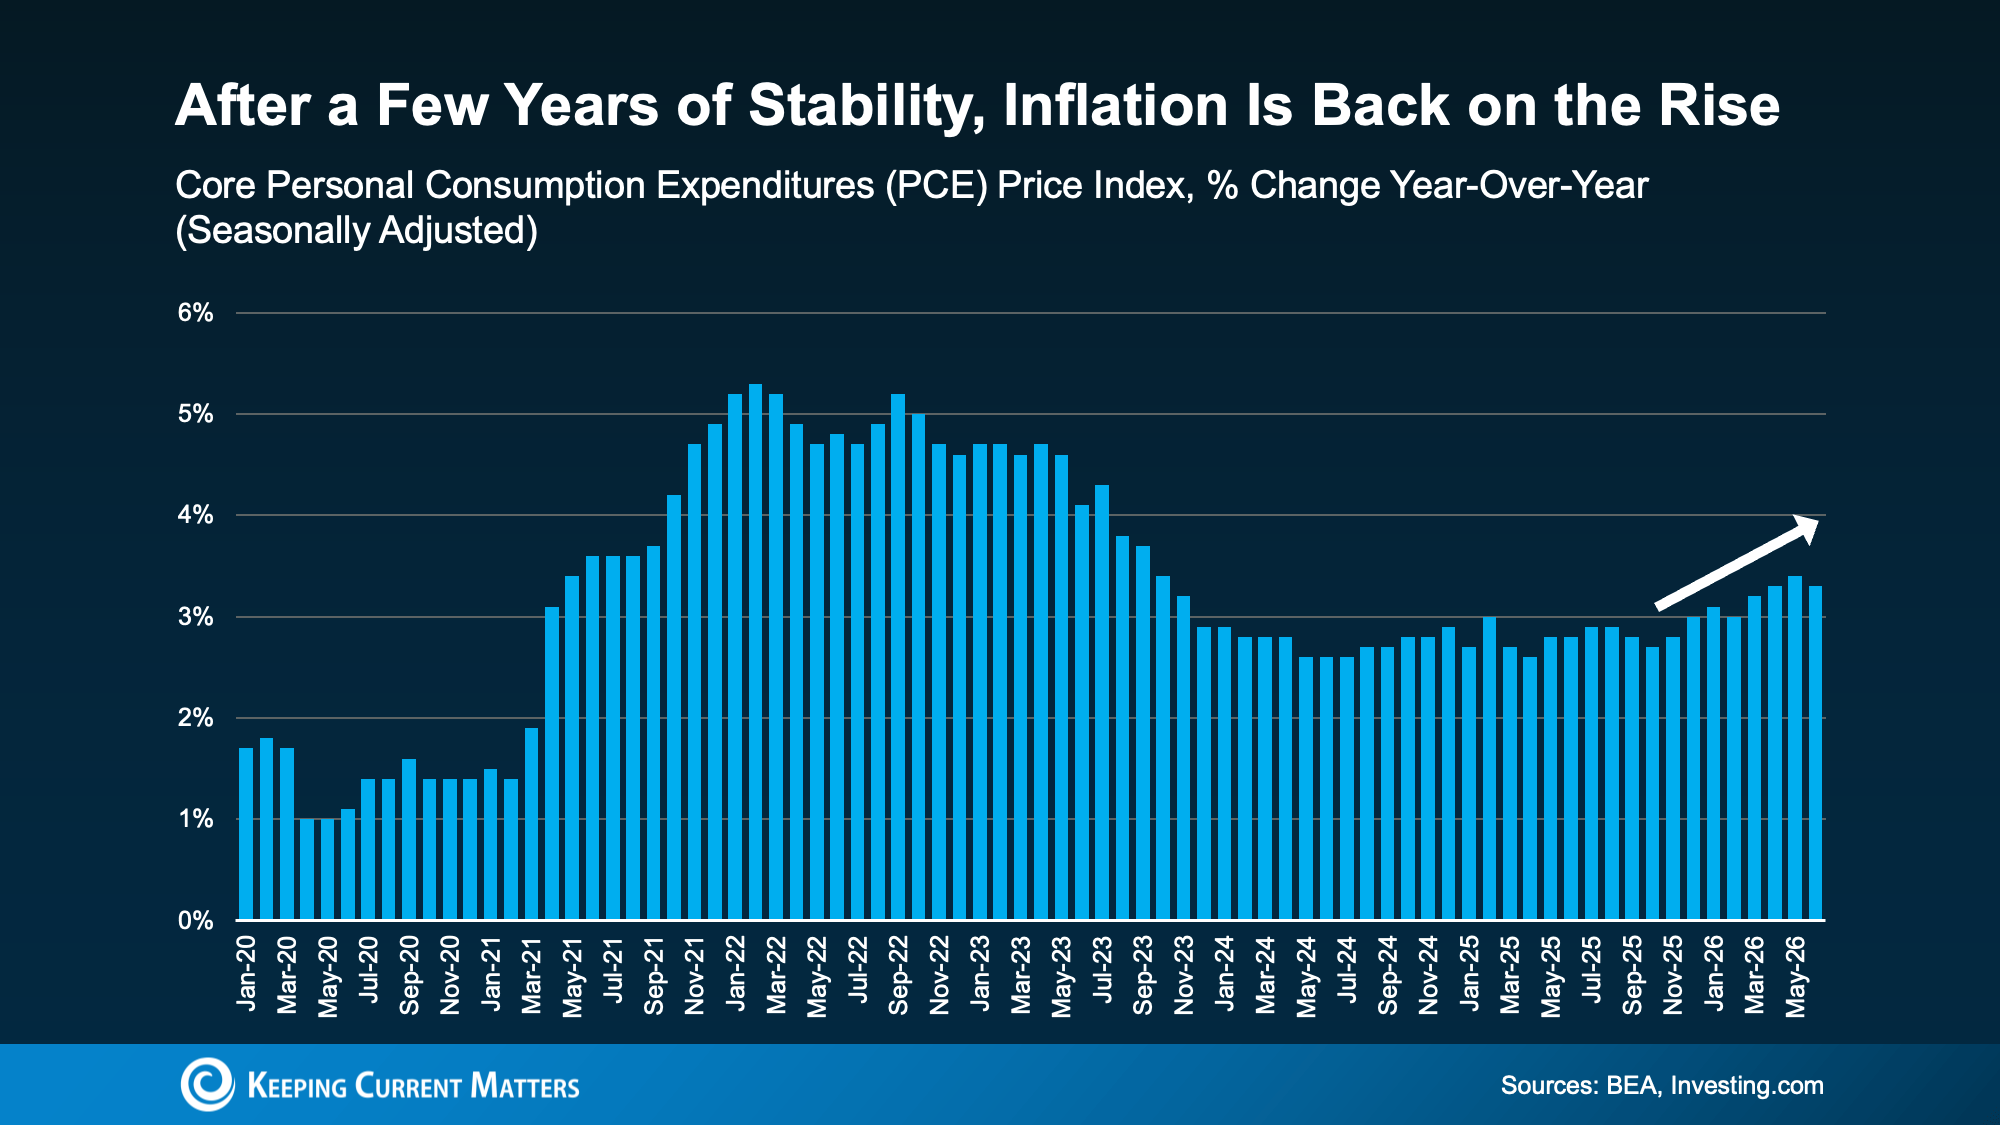
One reason experts aren't forecasting a significant decline in mortgage rates is inflation.
Generally, persistent inflation makes it more difficult for mortgage rates to move substantially lower.
After a period of relative stability between mid-2023 and late 2025, recent data cited by Keeping Current Matters shows inflation has been trending higher again.
Source: Investing.com, via Keeping Current Matters
Why should a homebuyer care about inflation?
Because mortgage rates don't move in isolation. Inflation, economic growth, Treasury yields, and expectations about future Federal Reserve policy can all influence the direction of borrowing costs.
Right now, some of the conditions that would typically support a major decline in mortgage rates simply aren't in place.
For buyers considering a move to Bluffton or Hilton Head Island, that makes it important to evaluate the market that's actually in front of you rather than building your entire buying strategy around a future rate that may or may not arrive.
3. Today's Mortgage Rates Are Closer to Historical Norms Than They Feel
This may require the biggest mindset shift.
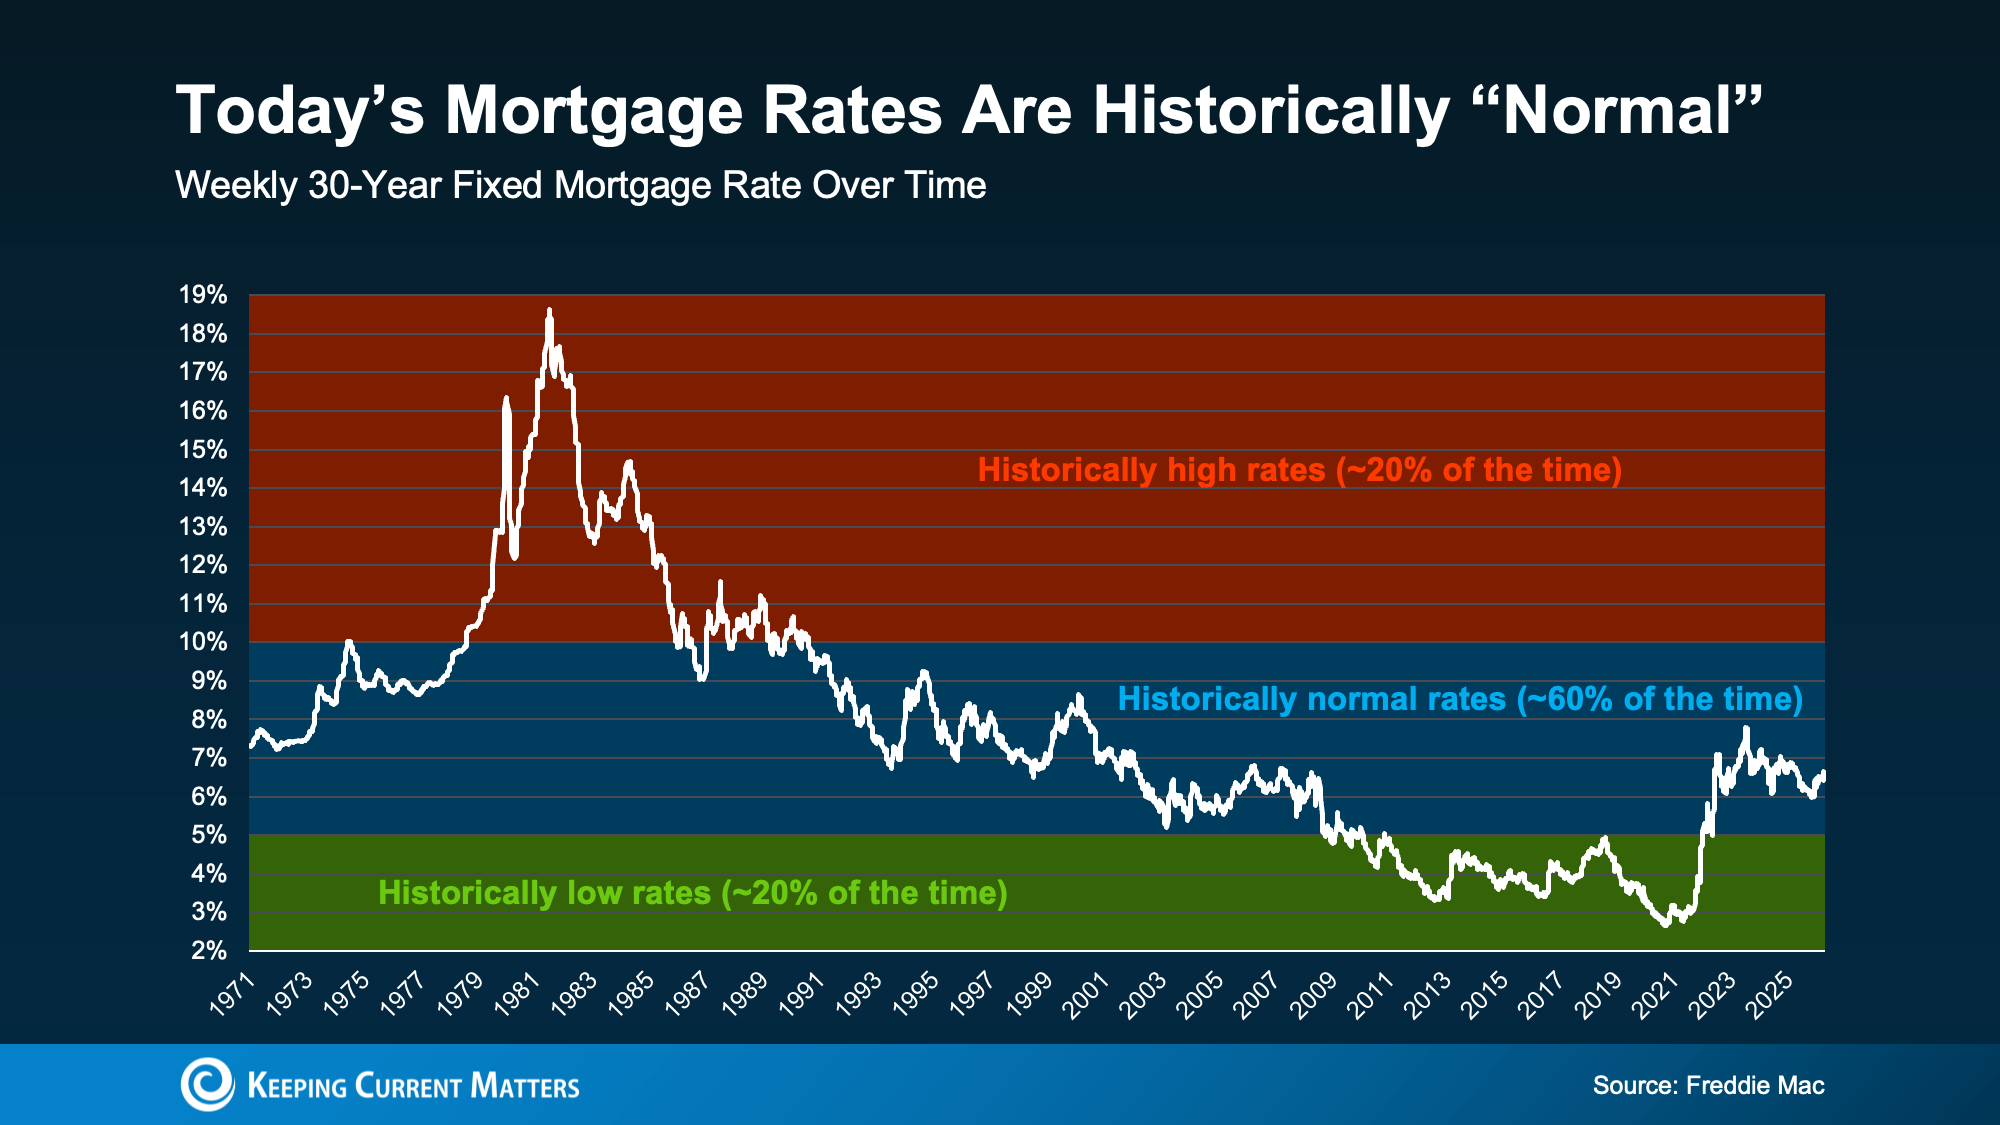
Today's mortgage rates feel high largely because buyers remember the exceptionally low rates available during and immediately following the pandemic.
Historically, however, those rates were the exception, not the rule.
Freddie Mac data highlighted by Keeping Current Matters shows that mortgage rates have spent much of their history between approximately 5% and 10%.
Source: Freddie Mac, via Keeping Current Matters
That doesn't suddenly make a 6% mortgage rate exciting. Your monthly payment matters, and affordability should always be part of the conversation.
But historical context does matter.
If your home-buying plan depends on mortgage rates returning to pandemic-era levels, you may be basing a major financial decision on market conditions that weren't historically normal to begin with.
Waiting Has a Tradeoff, Especially in the Lowcountry
This is where the conversation becomes much more local.
Waiting for a lower mortgage rate isn't automatically a bad strategy. But the mortgage rate is only one variable in a home purchase.
Inventory matters.
Home prices matter.
Negotiating leverage matters.
The specific property matters.
And in the Lowcountry, the community and lifestyle you're trying to buy into matter tremendously.
A buyer searching for a particular homesite in Colleton River, a waterfront property on Hilton Head Island, a home in Palmetto Bluff, or a specific location within Oldfield may not have dozens of comparable options available at any given time.
Sometimes the bigger question isn't:
"Will mortgage rates be lower next year?"
It's:
"If the right property becomes available now, does waiting put me in a better position?"
That's a very different conversation.
There May Be Other Ways To Improve Affordability
If rates are the primary reason you're waiting, it may be worth exploring strategies beyond simply postponing your purchase.
Depending on the property and your individual financial situation, buyers may be able to consider new-construction incentives, mortgage rate buydowns, adjustable-rate mortgages, or assumable mortgages.
Some builders may offer financing incentives or upgrades. In other situations, buyers may be able to negotiate concessions that can be applied toward certain closing costs or a rate buydown.
These options aren't appropriate for every buyer or every transaction, which is why it's important to evaluate them with a qualified lender.
The point isn't that you should find a workaround just so you can buy a house.
It's that waiting isn't your only option.
Should You Buy Now or Wait?
There's no universal answer.
If buying today would stretch your finances too far, waiting may absolutely make sense.
If you're unsure where you'll be living in a few years, buying may not make sense yet either.
But if you're financially prepared, you've found a community you love, and the right property becomes available, waiting solely because you're expecting dramatically lower mortgage rates deserves a closer look.
A good buying strategy considers the entire picture: your finances, the property, negotiating conditions, available inventory, your timeline, and your long-term plans.
Thinking About Buying in Bluffton or Hilton Head Island?
If you're considering buying a home in Bluffton, Hilton Head Island, or elsewhere throughout the South Carolina Lowcountry, we can help you evaluate more than what's happening with mortgage rates.
We help buyers understand the differences between communities, current inventory, recent sales, membership structures, amenities, boating and golf access, lifestyle considerations, and the other factors that can determine whether a property is truly the right fit.
Reach out to Kevin King Associates to start a conversation about what you're looking for, where you're considering buying, and whether today's market offers an opportunity that makes sense for you.
You don't need to have your timeline figured out. Sometimes the best place to start is simply understanding your options.
Posted by Kevin King on
Leave A Comment